Law Firms
Planning Partner Distributions Without Creating Tax Surprises
October 2026
Your law firm had a profitable year. So why are partners surprised by their tax bills?
It's a frustrating conversation, especially when everyone thought the firm was doing well. Then tax season arrives, and someone asks: "Why do I owe so much when I already took my distributions?"
The problem may not be how much money the firm earned. It may be how and when that money was distributed.
For law firm managing partners, distribution planning isn't just about dividing profits. It's about protecting the firm's financial health while helping partners prepare for their personal tax obligations.
Here's what to consider before approving the next round of distributions.
Download our Partner Distribution Planning Guide to review the numbers, questions, and decisions that deserve attention before your next partner meeting.
6 Ways Law Firms Can Plan Partner Distributions and Avoid Tax Surprises
Here are six ways firms can plan partner distributions to help partners avoid tax surprises.
Having a conversation with us before distributions are finalized can help identify issues that might otherwise go unnoticed.
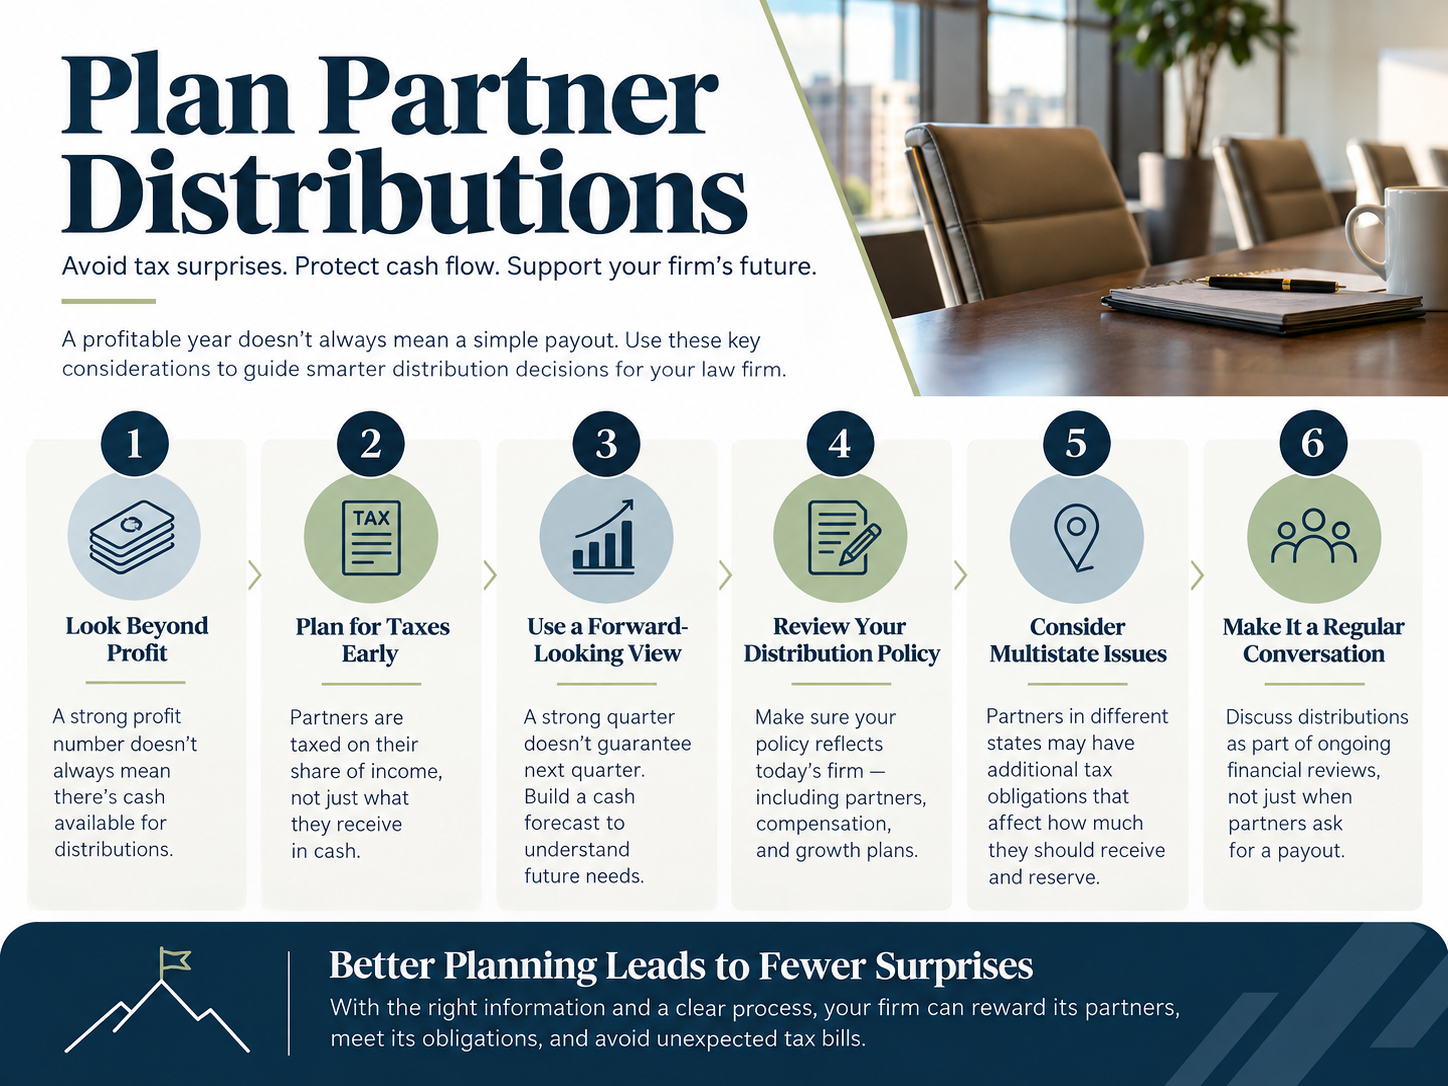
1. Stop Treating Profit and Available Cash as the Same Thing
A law firm can report a strong profit while still facing a cash shortage. Why?
Because profit doesn't tell you exactly how much money is sitting in the bank or how much of that money is available to distribute. And depending on the firm's accounting method, some reported income may not yet have been collected.
A profitable year doesn't automatically mean the firm can afford a large distribution. Before approving payments, managing partners can change the entire discussion by asking: "If we distribute this amount now, what will our cash position look like 30, 60, and 90 days from today?"
2. Plan for Taxes Before Partners Receive Their Distributions
One of the most common mistakes we see in firms is treating tax planning as something partners handle independently after receiving their payments. Yes, each partner is responsible for their own tax situation. But the firm can help make that responsibility easier to manage.
Consider establishing a process that includes:
- Estimating each partner's share of taxable income throughout the year.
- Reviewing whether partners are setting aside enough for federal and state taxes.
- Discussing estimated tax payment deadlines.
- Considering tax distributions under the partnership agreement.
- Revisiting projections when firm profitability changes.
Some firms establish a formal tax distribution policy to help partners cover estimated obligations. Others build tax planning into regular partner compensation and distribution discussions. The important part is making tax preparation an ongoing conversation rather than an unpleasant April discovery.
3. Don't Let One Strong Quarter Dictate the Entire Year
Imagine your law firm collects several large outstanding fees in October. Suddenly, the bank balance looks terrific. Partners see the numbers and begin discussing additional distributions before year-end.
But what happens if:
- The first quarter of the following year is slower?
- A major client delays payment?
- The firm needs to replace a senior associate or make a substantial technology investment?
A strong collection month doesn't guarantee strong cash flow next quarter.
Instead of relying on the current bank balance, use a rolling cash forecast to evaluate what's coming. Looking ahead 13 weeks provides a practical starting point. The forecast should account for expected collections, payroll, operating expenses, debt payments, and planned distributions.
The goal isn't to keep money away from partners. It's to avoid distributing money the firm will need back in 60 days.
4. Make Sure the Distribution Policy Matches How Your Firm Operates
When was the last time you reviewed your distribution policy? For some firms, the answer may be several years ago.
That's a problem if the firm has since added partners, changed its compensation model, opened another office, or shifted its practice mix.
An outdated policy can create confusion about:
- How often distributions are made.
- Whether payments are equal or based on individual performance.
- How much cash the firm retains.
- How tax-related payments are handled.
- What happens when a partner joins or leaves.
- Who approves special or year-end distributions.
Clear policies reduce the likelihood of disagreements and last-minute decisions. They also make it easier to explain why a profitable firm may need to retain some of its earnings. The policy should be reviewed alongside the firm's partnership or operating agreement and its tax structure.
5. Watch for the Hidden Complications of Multistate Partners
Does your firm have partners working in different states?
Partners may have tax filing or payment obligations in more than one state, depending on:
- Where the firm operates,
- How income is allocated, and
- Applicable state rules. Some states also require firms to make payments on behalf of certain partners.
These details can affect how much cash partners should reserve and how the firm plans its distributions. Don't assume every partner has the same tax situation.
6. Make Distribution Planning Part of Your Firm's Financial Meetings
Distribution planning shouldn't happen only when partners ask, "How much can we take?" It should be part of a regular financial review.
At a minimum, your leadership team should understand:
- How much profit the firm expects to generate.
- How much cash is available after upcoming obligations.
- Whether partner tax estimates need to change.
- How distributions compare with the firm's agreed-upon policy.
- Whether planned payments could affect next quarter's operations.
The conversation becomes more productive when everyone is working from the same information. Instead of debating whether partners deserve a larger distribution, you can discuss what the firm can responsibly afford.
Frequently Asked Questions About Law Firm Partner Distributions
Can law firm partners owe taxes on money they haven't received?
Yes. Partners in firms taxed as partnerships can owe income taxes on their allocated share of taxable profits even when the firm retains some of those profits for operating needs.
How often should law firms review partner distributions?
Quarterly reviews are a useful starting point, with additional reviews before significant or special distributions. Firms experiencing rapid growth, uneven collections, or cash flow challenges may benefit from more frequent discussions.
Should law firms keep a cash reserve before distributing profits?
Generally, yes. The appropriate reserve depends on the firm's payroll, operating expenses, collection patterns, debt obligations, and anticipated investments. There is no single reserve amount that works for every firm.
A Better Distribution Conversation Starts Before the Money Goes Out
No managing partner wants to tell colleagues that the firm distributed too much cash. And no partner wants to discover that a successful year produced a tax bill they weren't prepared to pay.
Both situations are easier to address when distribution planning happens before payments are approved.
At LMJ CPAs, we help law firms look beyond their current profits to understand cash flow, tax obligations, and the financial decisions that affect their partners.
Before you approve your next partner distribution, download our Partner Distribution Planning Guide to review the numbers, questions, and decisions that deserve attention before your next partner meeting.
Ready for a more informed discussion?
Contact LMJ CPAs to review your firm's distribution strategy and plan for the year ahead.